Online gambling has quietly become one of the more resilient corners of digital entertainment, expanding even as regulators tighten their grip and player expectations shift. Statista projects the sector will grow at a compound annual rate of 3.21% between 2025 and 2029, a modest but steady figure that masks a much more turbulent picture underneath: fragmented regulation, rapid technology adoption, and a business model under increasing scrutiny.
From Offshore Curiosity to Regulated Industry
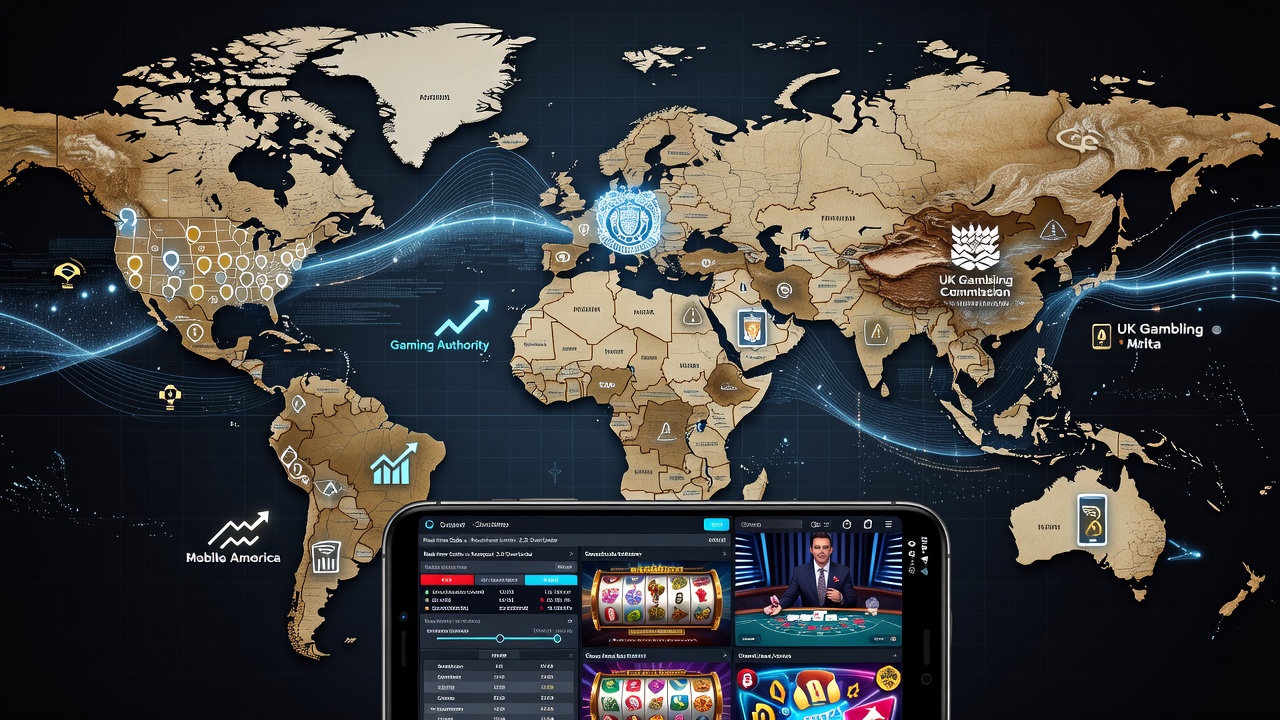
The industry's roots trace back to 1994, when Antigua and Barbuda passed the Free Trade and Processing Act, opening the door to licensed online gambling operators. Microgaming's early software and Intercasino's first real-money wager followed shortly after, establishing a template that regulators would spend the next two decades trying to catch up with. Malta's Gaming Authority, formed in 2001, and the UK Gambling Commission, established under the 2005 Gambling Act, became reference points for what a mature regulatory framework could look like. The 2018 repeal of PASPA in the United States accelerated state-by-state legalization of sports betting, while the pandemic pushed land-based operators online and normalized digital gambling across new demographics.
Two Segments, One Business Logic
Online casino products and sports betting remain the industry's two core pillars, each with distinct dynamics. Slots dominate casino platforms through simplicity and pacing, table games rely on customisable interfaces and side-bet variety, and live-dealer formats replicate the social atmosphere of physical casinos through real-time streaming. Sports betting has evolved beyond fixed odds into live betting and bet-builder tools that give bettors more control - and more ways to engage, which is precisely why regulators watch this segment closely for problem-gambling indicators.
Mobile, AI and the Fragmented Regulatory Map
Mobile now accounts for the majority of iGaming traffic, and platforms that underperform on smaller screens are structurally disadvantaged. Artificial intelligence increasingly shapes game recommendations and personalization, raising legitimate questions about data use and the line between tailored experience and manipulation of player behavior. Regulation, meanwhile, remains anything but uniform. The US and Canada regulate at the state and provincial level rather than nationally; Europe's established authorities in the UK, Malta, the Netherlands, Sweden, Spain and Germany contrast with fast-emerging markets like Brazil; Australia maintains a cautious stance, India regulates state by state, and much of Africa's growth centers on mobile-first sports betting.
- Non-compliance risks: weak Know Your Customer checks, inadequate responsible-gambling tools, misleading advertising
- Advertising restrictions tightening in the UK, Netherlands and Australia
- Rising cybersecurity exposure - phishing, account takeovers, DDoS attacks
Where the Pressure Points Lie
Growth in Brazil and interest across Mexico, Colombia and Argentina point to Latin America as the next regulatory frontier, but new markets also mean untested compliance regimes and higher operational uncertainty for operators entering early. Niche formats such as crash games are carving space alongside traditional RNG titles, giving smaller studios room to compete. None of this changes the underlying nature of the product: gambling outcomes remain governed by chance and house edge, regardless of how personalized or immersive the interface becomes. As AI, AR and VR reshape how games are built and played, the more consequential story may be regulatory - whether oversight of data use, marketing and player protection can keep pace with the technology it is meant to govern.